Financial Health for Women Entrepreneurs: A Practical Guide to Becoming Bank-Ready
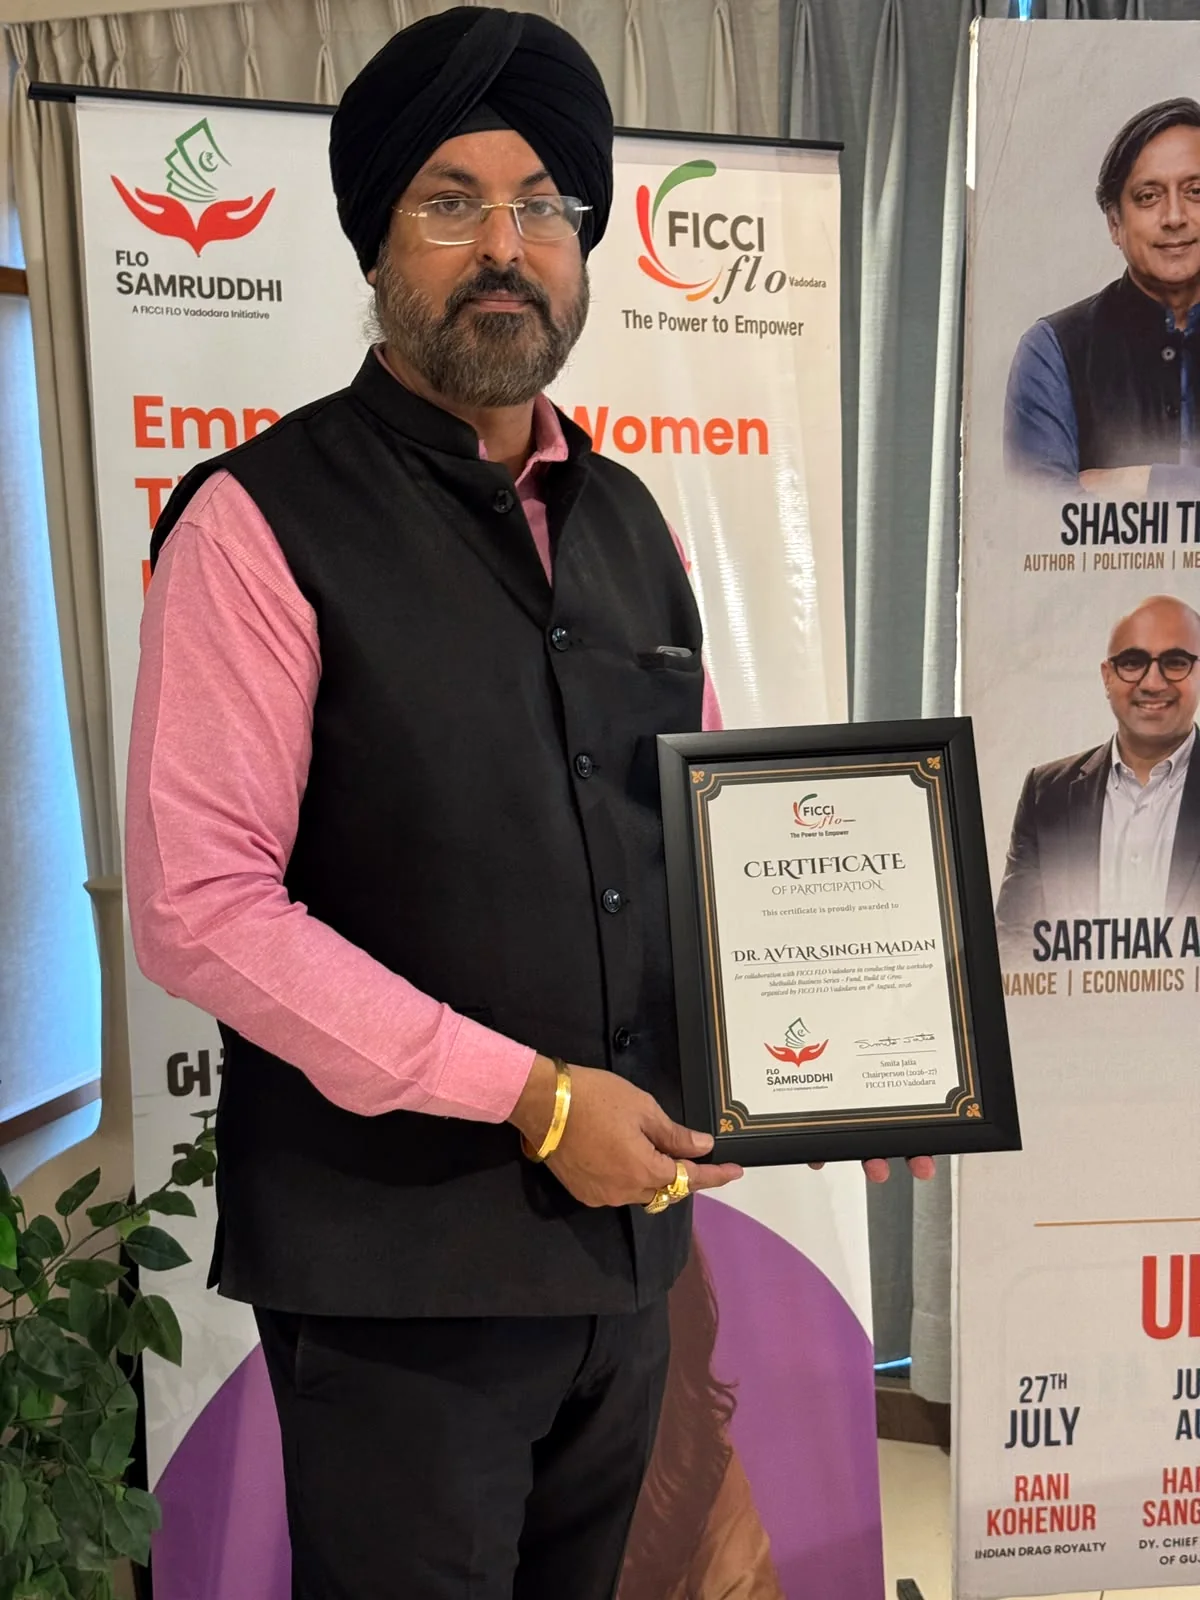
Cleaner records, stronger credit health and responsible funding, based on Dr. Avtar Madan's recent seminar for women entrepreneurs in Gujarat.
A woman can run a busy boutique, collect orders every day and still struggle when she asks a bank for a business loan.
The problem may not be the business. It may be the way the business appears on paper.
Customer payments enter a personal account. Household expenses and business costs get mixed. Tax returns are filed late. Sales are real, but the records do not tell the same story.
This is one of the most important messages I shared during a recent financial-literacy seminar for women entrepreneurs in Gujarat.
Your product matters. Your customers matter. Your hard work matters. But when you want outside finance, a bank must also be able to understand your numbers.
“Nishaan chook maaf. Nahi maaf nichu nishaan.”
Missing the target can be forgiven. Aiming too low cannot.
That does not mean taking the biggest loan available. It means building a business that is properly registered, financially visible and ready to use the right money at the right time.
Start with financial health, not a loan application
Many founders ask, “Which loan can I get?”
I would start with a different question: “Can your business show that it is ready to repay one?”
A loan is not proof that a business is healthy. It is a responsibility added to the business.
Before applying, you should be able to answer these questions without guessing:
- How much money came into the business during the last 12 months?
- What were the direct costs of producing or delivering your product?
- How much did the business spend on rent, salaries, marketing and other overheads?
- Which customers still owe you money?
- Which suppliers must you pay soon?
- How much cash will remain after the next three months of expected expenses?
- How much EMI can the business pay during a weak month?
If those answers are sitting in different notebooks, WhatsApp chats and personal bank accounts, fix that first.
The four-stage roadmap I shared at the seminar
The roadmap is simple: formalise, digitise, fund wisely and expand.
Each stage makes the next one safer.
1. Formalise the business
Choose a legal structure that fits the ownership, risk and future plans of the business. It may be a proprietorship, partnership, LLP or private limited company. The right choice depends on the business, so take advice from a chartered accountant or company professional before registering.
Keep the basics clean:
- Use the same legal name across PAN, GST, invoices, bank accounts and registrations.
- Complete Udyam registration if the enterprise qualifies as an MSME.
- File income-tax returns on time.
- Register for GST when the law requires it or when it makes commercial sense after professional advice.
- Keep licences, rent agreements and ownership documents current.
The Government of India says Udyam registration is free, paperless and based on self-declaration. Use the official government portal only. Private websites may charge money for a registration that the government provides without a fee.
Formal records do not make a weak business strong. They make a real business visible.
2. Digitise the money trail
Open and use a bank account meant for the business.
Route business sales into that account. Pay suppliers and business expenses from it. Avoid using the same account for school fees, groceries, personal travel and business stock.
This separation gives you three useful things:
- A clearer view of cash flow.
- Cleaner records for tax and accounting work.
- A bank statement that a lender can actually study.
Use basic accounting software or a disciplined spreadsheet. Record sales, expenses, receivables, payables and stock regularly. A small business does not need a complicated finance department. It does need numbers that agree with its bank statements and tax records.
Digital records also help you spot a problem early. Rising sales can hide falling cash if customers are taking longer to pay.
3. Fund wisely
Borrowing should solve a defined business need.
“I need money for growth” is not a plan. “I need ₹8 lakh for two machines that will add a stated production capacity, plus ₹3 lakh of working capital” is a plan a lender can examine.
Match the type of finance to the use:
- Use a term loan for machinery, equipment or another long-life asset.
- Use working-capital finance for stock, raw material and the gap between paying suppliers and receiving customer payments.
- Consider a loan against property only after understanding that the property is security and may be at risk if repayment fails.
- Be careful with personal loans and credit cards for business expansion. Fast money can become expensive money.
Do not borrow the highest amount offered. Borrow the amount the business can use well and repay from a realistic cash-flow plan.
4. Expand after the base is ready
Growth is not only a bigger Instagram page or another exhibition stall.
It can mean selling through formal trade channels, supplying another business, entering a new city, adding production, exporting or building a team that does not depend on the founder for every task.
Expansion needs evidence:
- Which product has steady demand?
- What will the expansion cost?
- How long before the new capacity earns money?
- What happens if sales start three months late?
- Who will manage operations while the founder sells?
Run the weak-month calculation before the best-case calculation.
Treat CIBIL as part of your business reputation
For many small businesses, the promoter's personal credit profile matters because the business may have a limited borrowing history.
A CIBIL Score ranges from 300 to 900. CIBIL says a score above 750 is generally considered good, but it does not approve or reject a loan. The lender makes that decision after considering the full application.
Check your report before applying. Look for:
- late or missed payments;
- loans or cards you do not recognise;
- incorrect outstanding balances;
- high credit-card utilisation;
- several recent loan enquiries; and
- old accounts that were not updated correctly.
Pay every EMI and card bill on time. Keep card balances under control. Do not submit applications to many lenders in panic. If the report contains an error, raise a dispute through the official process and keep the supporting documents.
A high score does not replace income, cash flow, collateral or scheme eligibility. It gives the lender one more reason to study the proposal seriously.
ITR, Udyam and bank statements must tell one story
A lender may compare your application with your bank statements, GST returns, income-tax returns and business records.
Large sales claimed in a project report will raise questions if the bank account shows very little activity. A strong turnover claim will not help if returns are missing. Regular cash deposits without clear invoices may need an explanation.
Do not create numbers only when a loan is needed.
Build the record month by month.
A clean file normally includes:
- PAN and Aadhaar of the applicant or promoters;
- business registration and constitutional documents;
- Udyam registration, where applicable;
- GST returns, where applicable;
- income-tax returns;
- recent personal and business bank statements;
- proof of business address and required licences;
- existing loan statements;
- machinery quotations or supplier estimates;
- a project report explaining the business and proposed use of funds; and
- projected profit, cash flow and repayment capacity.
The exact list changes by lender, scheme and business type. Ask for the lender's current checklist before spending money on reports or certificates.
A project report should answer hard questions
A project report is not a decorative file.
It should show what the business sells, who buys it, what the owner has already invested, how much funding is needed and how the loan will be repaid.
Keep the assumptions honest.
If monthly sales are currently ₹3 lakh, a forecast of ₹15 lakh next month needs strong evidence. Show purchase orders, signed contracts, production capacity or a clear sales pipeline. Do not raise the number because a higher projection may support a larger loan.
The same rule applies to costs. Include installation, deposits, licences, staff, marketing, working capital and the time needed before new equipment starts earning.
Banks do not only finance optimism. They assess repayment risk.
Government-backed finance: what is current and what has changed
Scheme names travel faster than scheme rules.
A WhatsApp post may say “₹20 lakh without collateral” and leave out the condition that changes the whole answer. Always read the current official rule before applying.
Status verified from official sources on 12 August 2026.
Pradhan Mantri MUDRA Yojana
ActiveCollateral-free institutional credit supports eligible micro-enterprise activities. Shishu goes up to ₹50,000, Kishore above ₹50,000 to ₹5 lakh, and Tarun above ₹5 lakh to ₹10 lakh. Tarun Plus covers above ₹10 lakh to ₹20 lakh only for entrepreneurs who previously took and successfully repaid a Tarun loan.
Check: Business activity, lender policy, repayment capacity and the prior-loan condition for Tarun Plus.
Read the official PMMY informationPrime Minister's Employment Generation Programme
Applications availableFor a new unit, the revised guideline permits project cost considered for margin-money subsidy up to ₹50 lakh in manufacturing and ₹20 lakh in business or services. Women fall under the special category, for which contribution and subsidy rules can differ by urban or rural location.
Check: Activity and applicant eligibility, current district intake, contribution, training, subsidy conditions and bank sanction.
Use the official PMEGP portalCGTMSE Credit Guarantee Scheme
ActiveEligible member lenders can obtain guarantee cover for qualifying micro and small enterprise credit facilities up to ₹10 crore. The framework shows higher guarantee coverage for women entrepreneurs. CGTMSE does not hand a loan directly to the entrepreneur.
Check: Whether the lender is a registered member, the facility qualifies, guarantee fees, security structure and the lender's own credit decision.
Read the official CGTMSE coverageStand-Up India
Original period endedThe official Department of Financial Services page says the scheme operated up to 31 March 2025. It records a proposed replacement for five lakh first-time women, SC and ST entrepreneurs, with term loans up to ₹2 crore, but the proposal was still under preparation in its 5 February 2026 update.
Check: Do not assume the old scheme or announced replacement is open. Confirm the latest position before preparing an application.
Check the official Stand-Up India pageViksit Gujarat Industrial Policy 2026
Benefit details need checkingGujarat's official investment-policy repository lists the 2026 policy. It includes support themes for MSMEs, startups, innovation and women entrepreneurs. Eligibility depends on the relevant government resolution, business category, location, investment and application timing.
Check: Obtain the current government resolution and written eligibility guidance before including any subsidy in a project budget.
Open Gujarat's official policy repositoryRemember: A government guarantee is not the same as a government loan. “Collateral-free” does not mean “assessment-free”. A subsidy should not be treated as cash already received.
Common mistakes that make a good business look weak
Mixing home and business money
This hides the real profit and makes cash flow difficult to explain.
Applying before the documents agree
Different names, addresses, turnover figures or ownership details slow the review and create avoidable questions.
Asking for a loan without a use-of-funds plan
The lender needs to know where the money will go and how that spending will improve the business's ability to repay.
Depending on one customer
If one buyer provides most of the revenue, show what happens if that buyer delays payment or leaves.
Treating the sanctioned limit as money that must be spent
Unused debt costs less than badly used debt. Draw and spend only against a planned need.
Believing an agent can guarantee approval
No consultant, portal or middleman can honestly promise a bank sanction or government subsidy. Use official portals. Keep receipts. Never share an OTP with an unknown person.
Your 30-day bank-readiness checklist
Do not begin with ten loan applications.
Begin with one clean file.
Week 1
- Separate personal and business transactions.
- Review your CIBIL report.
- List every liability.
- Write down average monthly sales, expenses and cash left.
Week 2
- Check that PAN, GST, Udyam, bank and business names match.
- Bring bookkeeping up to date.
- Discuss compliance gaps with your accountant.
- Collect relevant bank statements.
Week 3
- Define the exact use of funds.
- Collect machinery, equipment or stock quotations.
- Prepare a base case and a weak-sales case.
- Calculate an EMI the business can pay.
Week 4
- Compare schemes and normal bank finance.
- Confirm current eligibility on official portals.
- Ask lenders for charges and document lists in writing.
- Submit a focused application.
A note from Dr. Avtar Madan
Do not play small. Do not grow blindly.
Strong businesses are built on good records, controlled cash flow and clear decisions. Funding can help a prepared business move faster. It cannot repair weak numbers by itself.
I have spent more than 25 years working across banking and financial advisory, guided more than 80,000 clients and worked with a network of over 50 banking partners. The lesson I keep seeing is simple: the best time to organise your financial file is before you urgently need money.
Take your last six months of bank statements and business records. Sit with your accountant or financial adviser. Find the first gap a lender would question, and fix that gap this week.
Independent media coverage
The seminar in the news
Pradesh24 Gujarati reported on the workshop and its focus on financial discipline, financial health, bank loans and government schemes for women entrepreneurs. This is independent event coverage, not a video published by Dr. Avtar Madan.